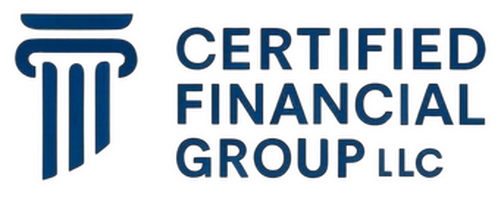
Guide to Annuities
Annuities can play a role in retirement income planning when used appropriately. Explore the basics, common types, and key questions to consider before making a decision.
Certified Financial Group, LLC
Annuities, explained.
Your goals, considered.
Annuities aren’t all the same. Understanding their differences is the first step toward deciding whether one belongs in your retirement plan.
Begin With the Purpose
What do you need your money to do?
An annuity is a contract with an insurance company. Its role in your plan depends on the contract’s features and the financial need you want to address.
Turn resources into payments
Income annuities provide payments beginning now or later. Depending on the option selected, payments may continue for a set period or for life.
- Consider when income needs to begin.
- Compare individual and joint-life options.
- Review access to funds and benefits for heirs.
Set money aside for later
Deferred annuities can hold assets for future use. Their interest or investment performance, risks, and withdrawal rules depend on the type selected.
- Understand how value can grow or decline.
- Review your time horizon and liquidity needs.
- Consider available future income features.
Understand the Differences
Three common approaches to accumulation.
These categories work differently. Compare the actual contract—not just its name or headline benefit.
Multi-Year Guaranteed Annuity
A MYGA provides a stated interest rate for a specified guarantee period.
- Review: The rate and guarantee term.
- Consider: Renewal provisions.
- Understand: Withdrawal limits and surrender charges.
Fixed Indexed Annuity
Interest credits depend partly on an index and the contract’s formula. You are not investing directly in the index.
- Review: Caps, participation rates, and spreads.
- Consider: Which terms may change at renewal.
- Understand: Charges can still reduce contract value.
Variable Annuity
Account value depends on selected investment options and can rise or fall. Investment losses are possible.
- Review: Investment choices and risks.
- Consider: Contract, investment, and rider expenses.
- Understand: Any guarantees and their conditions.
Look at the Formula
Index performance and credited interest are different.
A fixed indexed annuity uses contract rules to calculate interest. Three terms commonly shape that calculation.
A limit on interest
A cap sets the maximum interest credited for a defined period under the selected strategy.
A share of index gains
The participation rate determines how much of a measured index increase enters the interest calculation.
A deduction in the formula
A spread reduces the index-based result before credited interest is determined under the contract’s rules.
Income With Intention
Compare how income works—not just the payment.
An income annuity and an optional lifetime income rider can approach retirement income differently. Compare access to funds, costs, payment rules, and what may remain for beneficiaries.
- Income annuity: Review the payout option and what you give up in exchange for the payment stream.
- Income rider: Understand its cost, withdrawal limits, and conditions for maintaining the benefit.
- Benefit base: Ask how any income calculation value differs from the cash value you can access.
At Certified Financial Group, LLC, the conversation begins with your income needs and the flexibility you want to retain.
A Better Starting Point
Five questions worth asking.
A useful comparison makes the benefits and tradeoffs equally clear.
-
What specific need does this address?
Identify the role you expect the contract to play within your overall retirement plan.
-
How accessible is my money?
Review withdrawal allowances, surrender periods, and the effect of taking out more than permitted.
-
What are the total costs?
Ask about contract charges, optional benefits, investment expenses, and withdrawal-related costs.
-
Who supports the guarantees?
Understand the issuing insurer’s obligations, financial strength, and benefit conditions.
-
What happens to my spouse or beneficiaries?
Compare continuation options and death benefits before selecting an income arrangement.
Keep the Whole Plan in View
Details to discuss before deciding.
How should taxes fit into the discussion?
Review how the contract would be funded and how you expect to receive money from it. Coordinate those decisions with your tax professional rather than assuming every annuity receives the same tax treatment.
What about required minimum distributions?
If retirement-account assets are involved, ask how applicable distribution requirements interact with the contract’s withdrawal provisions and income features.
Should I add an optional rider?
Compare what the rider provides with its cost and conditions. Ask to see the option with and without the rider so you can evaluate its purpose in your plan.
What if I already own an annuity?
Bring the current contract and a recent statement. Review existing benefits, charges, and restrictions before considering any changes.
A Personal Conversation
Let’s make the details easier to understand.
Meet with David Anderson at Certified Financial Group, LLC to discuss your priorities, review your questions, and consider how available options fit your retirement plan.
davidcfp@gmail.comYour Family. Your Priorities.
A thoughtful plan for
the people who matter.
Behind every financial decision is something personal: time with family, a meaningful retirement, or the future you want to help create for the next generation.
At Certified Financial Group, LLC, we begin by listening. We take the time to understand your priorities, explain your options, and help you plan with the people you care about in mind.
- Personal attention A conversation centered on your life.
- Clear guidance Options explained in everyday language.
- Ongoing support Room to adjust as your priorities evolve.
Good planning begins with getting to know you.
Share your goals, bring your questions, and let’s explore your next steps together.